John Ternus, speaking alongside CFO Kevan Parekh, tempered optimism during the latest earnings call. Although price hikes helped the company edge past Wall Street expectations for the September quarter, leadership cautioned that services growth is decelerating. Rising memory costs are simultaneously putting pressure on gross margins, signaling a period of reduced profitability that weighed heavily on market sentiment.
Beyond hardware margins, strategic concerns loom over Apple’s artificial intelligence trajectory. While the company previously enjoyed investor patience regarding its AI spending, the current iteration of Siri is underperforming against competitors like Instinct and Muse. Furthermore, ongoing regulatory battles continue to threaten the App Store’s fee structure, which remains the primary engine of the firm’s services division.
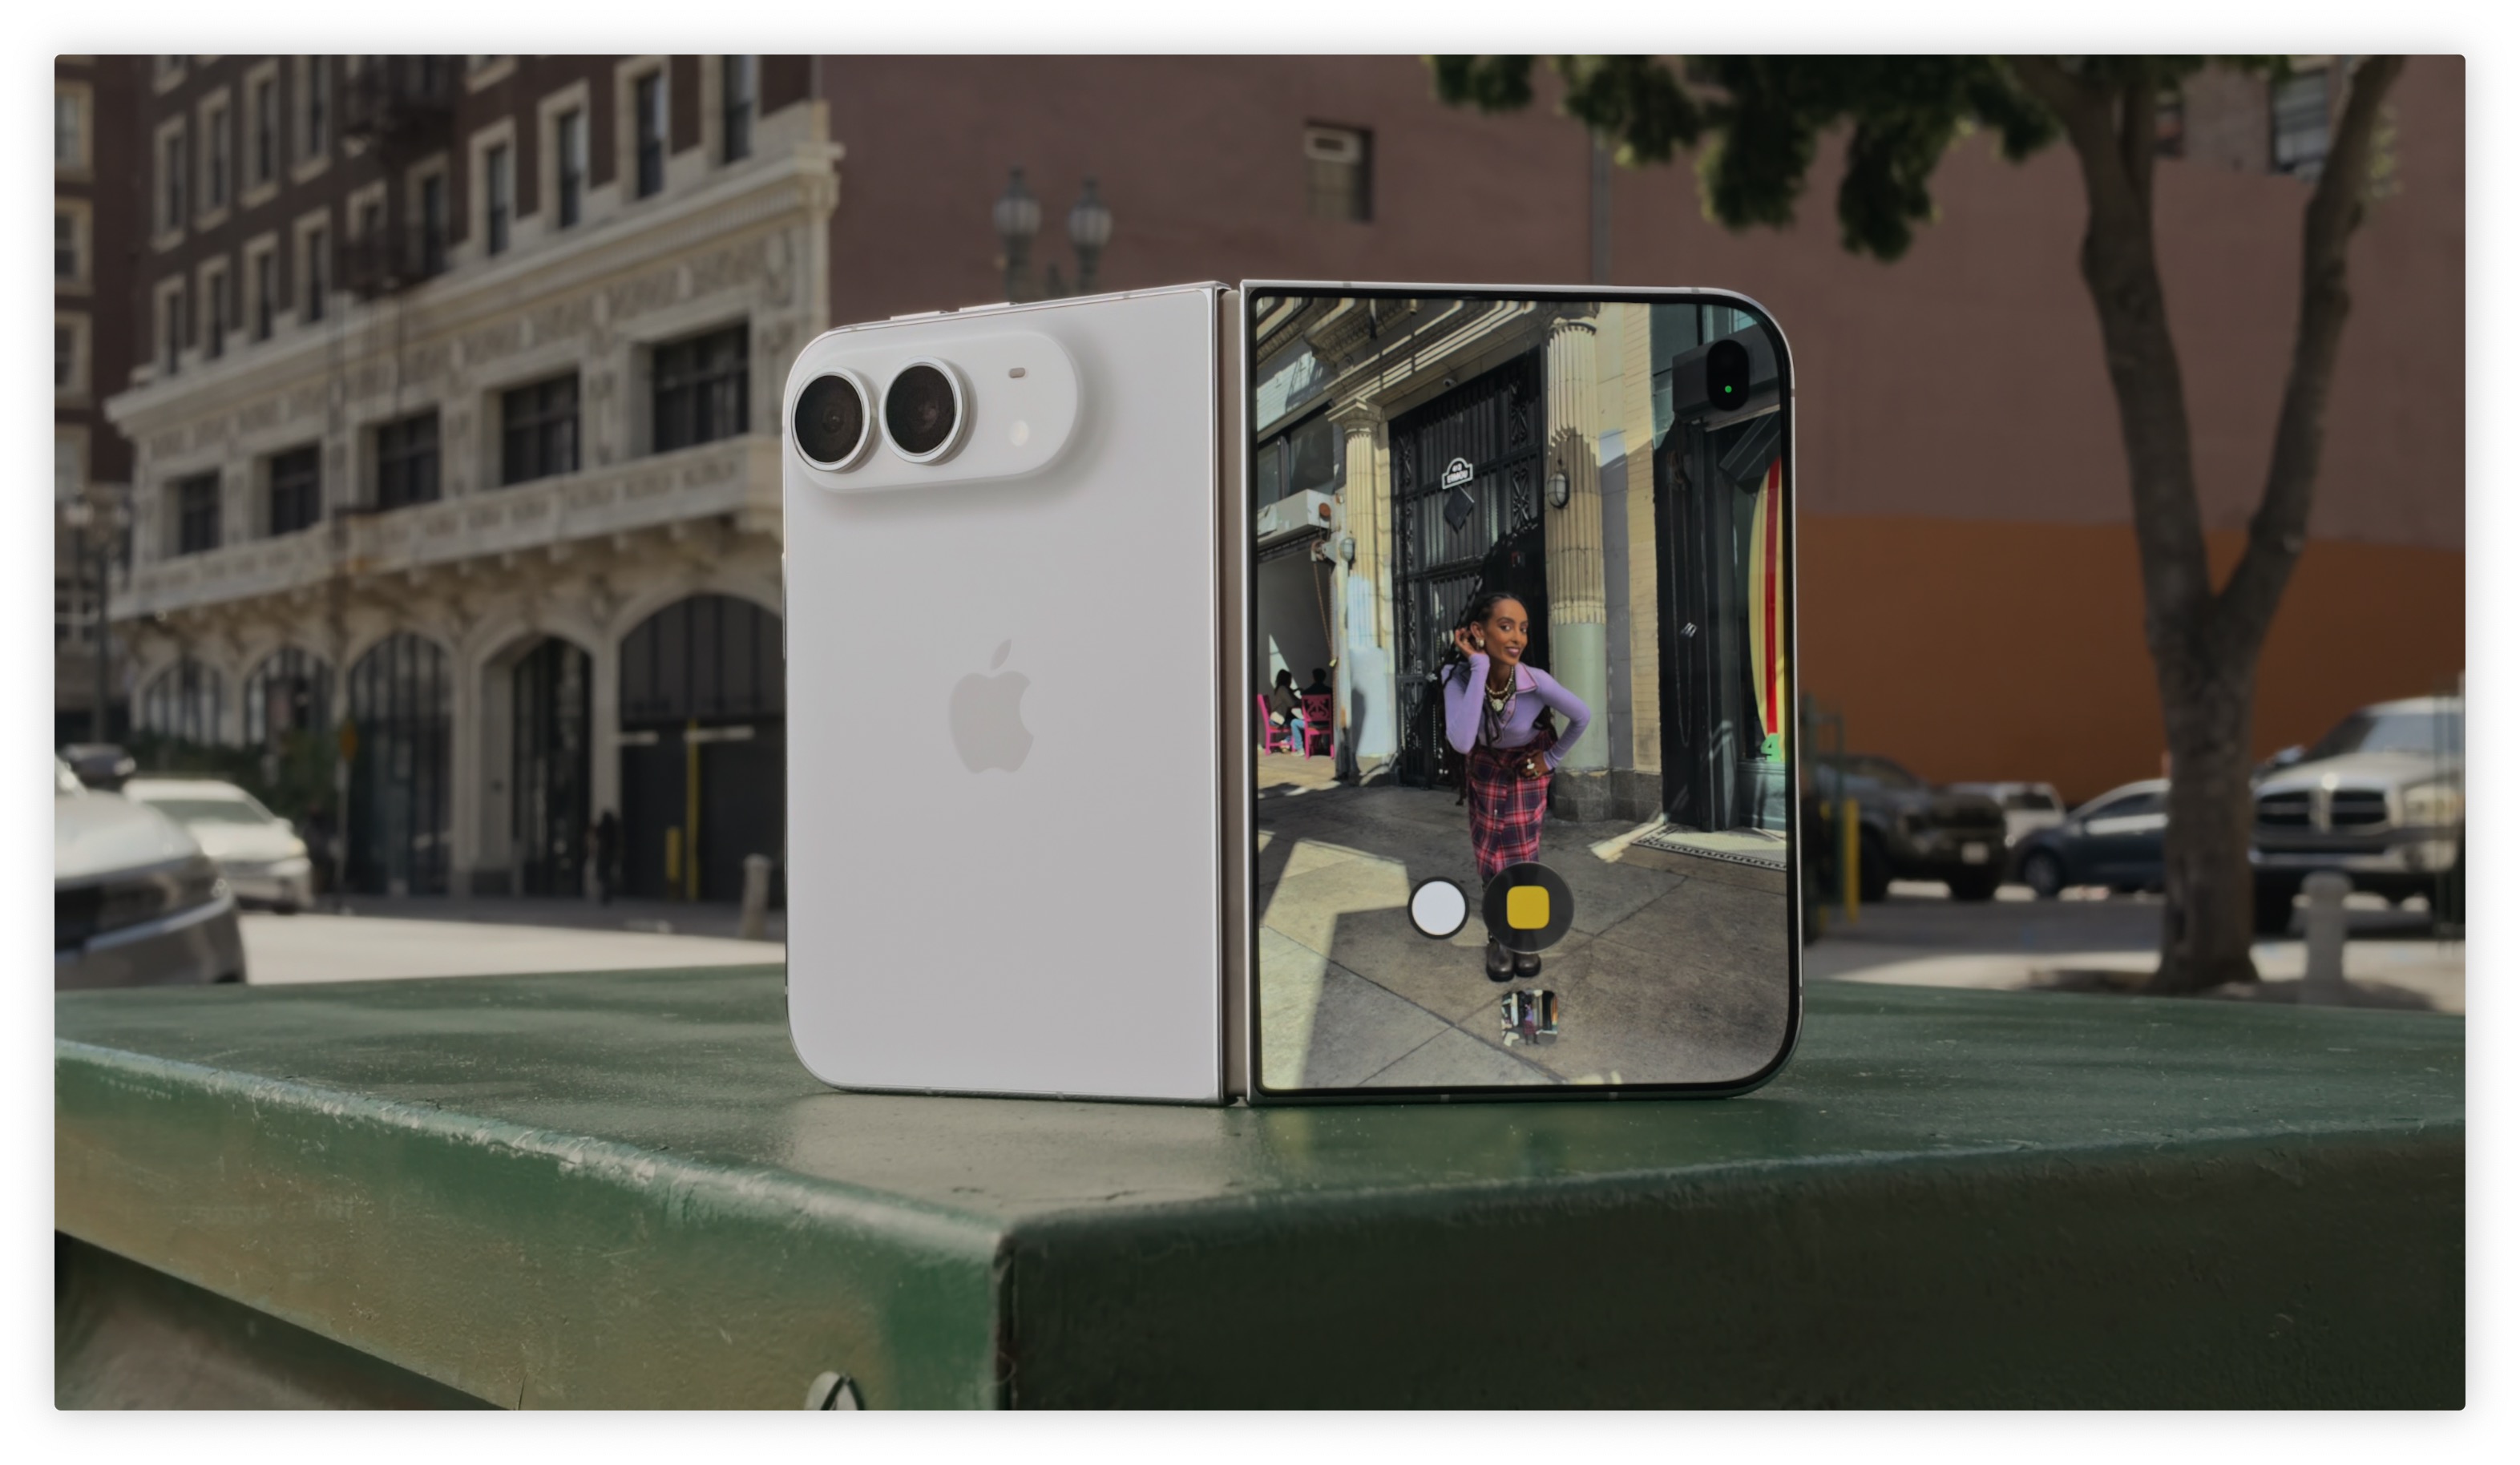
Despite the commercial success of the foldable iPhone Duo, analyst Martin Yang of Oppenheimer maintains a cautious outlook on the stock. With investors currently paying $36 for every $1 of projected future earnings, Yang suggests the price point leaves little room for further upside, casting doubt on whether current hardware momentum can offset broader structural headwinds.
Comments (0)
No comments yet. Be the first!